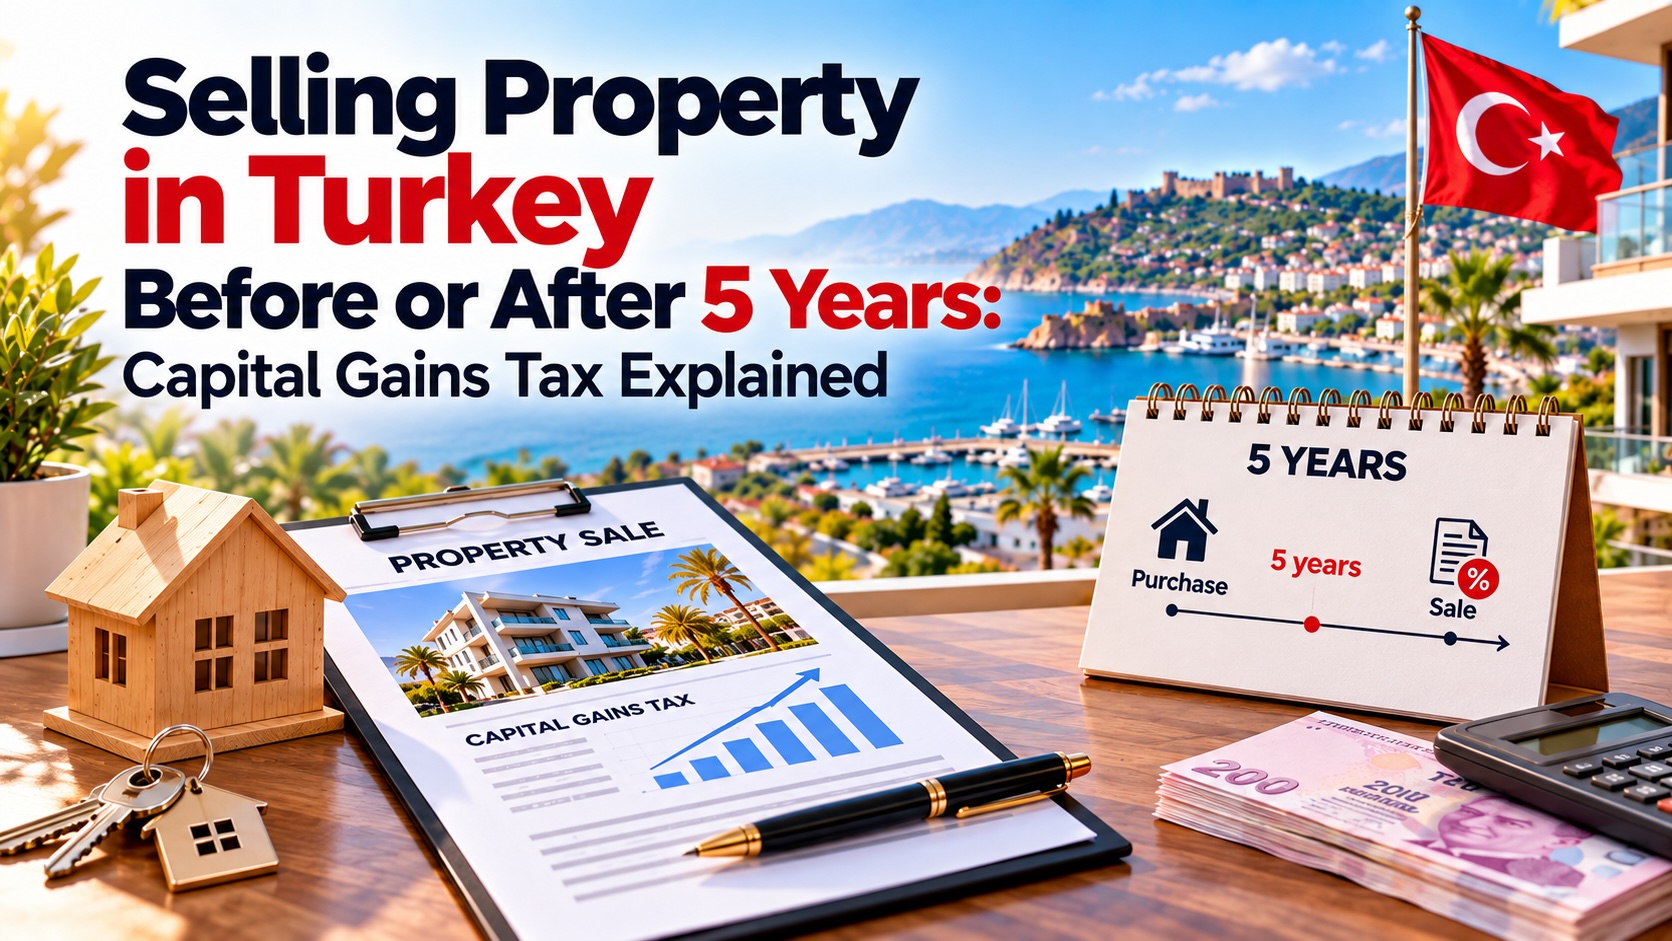
Selling Property in Turkey Before or After 5 Years: Capital Gains Tax Explained
Short answer: If an individual sells a property in Turkey more than five years after acquiring it, the resulting gain is generally outside the scope of Turkish capital gains tax. If the property is sold within five years, the gain may be taxable. However, tax is not simply calculated on the difference between the original purchase price and the sale price. The acquisition cost may be adjusted using Türkiye’s Domestic Producer Price Index (Yİ-ÜFE), certain seller-paid expenses and taxes may be deducted, and a TRY 150,000 capital gains exemption applies for 2026.
This makes the acquisition date particularly important for anyone planning to sell a house, apartment or land in Turkey. Foreign property owners are also subject to these rules when the relevant conditions apply.
Do You Pay Capital Gains Tax When Selling Property in Turkey?
It depends primarily on how the property was acquired, how long it has been owned and whether the transaction is considered a private disposal rather than a commercial property trading activity.
For an individual who purchased a property for consideration and holds it outside a business, a gain arising from a sale within five years of the acquisition date can fall within Turkey's capital gains tax rules.
If the property is sold after the five-year period has passed, the income from the sale is generally no longer treated as a taxable capital gain under this rule.
This is commonly referred to as the 5-year property rule in Turkey.
What Is the 5-Year Property Tax Rule in Turkey?
The rule is relatively straightforward in principle:
- Sell within 5 years: the gain may be subject to income tax as a capital gain.
- Sell after 5 years: the gain is generally outside the scope of capital gains taxation under this rule.
Importantly, the five-year period is calculated by calendar days, not simply by comparing calendar years.
For example, buying a property sometime in 2022 and selling it sometime in 2027 does not automatically mean that five years have passed. The exact acquisition and disposal dates must be checked.
When Does the 5-Year Period Start?
As a general rule, the acquisition date used for capital gains purposes is the date on which the property is registered in the owner's name at the Land Registry.
However, there are exceptions.
If the property was physically delivered and put into the owner's actual use before the title deed registration, the earlier date may in certain circumstances be accepted as the acquisition date, provided that actual use can be documented.
Evidence can include documents such as delivery records and utility connections or bills.
This distinction can become particularly important with newly constructed properties where physical delivery and title deed registration take place on different dates.
What Happens If You Sell Property in Turkey Before 5 Years?
Selling within five years does not mean that the entire sale price becomes taxable income.
The taxable calculation starts with the gain made on the disposal.
In simplified terms:
Sale proceeds – adjusted acquisition cost – deductible seller expenses/taxes – applicable annual exemption = taxable capital gain
The actual calculation can therefore be considerably different from simply subtracting the price shown on the old title deed from the new selling price.
How Is Capital Gains Tax Calculated on Property in Turkey?
There are several stages to the calculation.
1. Determine the acquisition cost
The starting point is the amount paid to acquire the property.
2. Check whether the acquisition cost can be indexed
Turkish tax rules allow the acquisition cost to be adjusted using the Domestic Producer Price Index, known in Turkey as Yİ-ÜFE, subject to the applicable statutory conditions.
This adjustment is important because it can increase the tax-recognised acquisition cost and therefore reduce the calculated capital gain.
3. Deduct eligible expenses, taxes and fees
Expenses relating to the disposal that remain with the seller, together with qualifying taxes and fees paid by the seller, can be taken into consideration when determining the gain.
4. Apply the annual capital gains exemption
For income earned in 2026, the capital gains exemption is TRY 150,000.
If the calculated gain falls within the exemption after the relevant calculations, an income tax liability may not arise under the capital gains rules.
5. Determine the taxable amount
Any remaining taxable gain is subject to the applicable Turkish income tax rules for that year.
Because tax brackets and annual exemptions can change, sellers should always use the figures applicable to the year in which the sale actually takes place.
Example: Selling a Property in Turkey Before 5 Years
Consider a simplified example.
An owner buys an apartment for TRY 4,000,000 and sells it four years later for TRY 7,000,000.
It would be incorrect to automatically assume that the taxable gain is TRY 3,000,000.
Before determining the taxable gain, the acquisition cost may need to be adjusted according to the applicable Yİ-ÜFE rules. Eligible seller-paid expenses, taxes and fees are then taken into account, followed by the annual exemption.
Only after these adjustments can the amount potentially subject to income tax be determined.
This is why the tax calculation should be made using the actual acquisition date, sale date, documented costs and the relevant index figures rather than a simple purchase-price-versus-sale-price comparison.
What Happens If You Sell Property After 5 Years?
For an individual holding a property outside a business, a property acquired for consideration and sold after the applicable five-year holding period is generally outside the scope of capital gains taxation.
For example, if the applicable acquisition date is 10 March 2020 and the property is sold after the five-year period has fully elapsed, the gain is generally not taxed as a capital gain under this rule.
This can make the exact sale date financially significant for owners who are approaching the end of their five-year holding period.
Does the 5-Year Rule Apply to Foreign Property Owners?
Foreign ownership does not by itself create a separate five-year capital gains regime.
Foreign individuals selling property in Turkey should therefore check the same fundamental issues: how the property was acquired, its acquisition date, the date of disposal, whether the activity could be considered commercial and whether any relevant exemption applies.
For international buyers who are still at the acquisition stage, understanding the future tax implications before purchasing can be useful. Our property buying guide for foreign buyers explains the broader acquisition process.
Do You Pay Capital Gains Tax on Inherited Property in Turkey?
The five-year rule does not apply in the same way to property acquired without consideration, such as through inheritance.
Under Turkish capital gains rules, gains arising from the disposal of property acquired without consideration are not treated as capital gains under this regime.
This means that an inherited property can fall outside these capital gains provisions even if it is sold within five years.
However, inheritance and transfer taxes are separate issues and should not be confused with capital gains tax arising from a later property sale.
Does Changing from Kat İrtifakı to Kat Mülkiyeti Restart the 5-Year Period?
Not necessarily.
If a property is registered as kat irtifakı and is later converted to kat mülkiyeti, the original kat irtifakı registration date can remain the relevant acquisition date for capital gains purposes.
Therefore, property owners should not automatically assume that the date printed on a later title deed starts a completely new five-year period.
There are, however, situations involving a genuine change in the legal nature of a property where the acquisition-date analysis can be different. The specific title deed history should therefore be reviewed before calculating tax.
Does Selling After 5 Years Mean the Property Sale Has No Taxes or Costs?
No. This is an important distinction.
The five-year exemption discussed here concerns the treatment of the seller's gain as capital gains income.
It does not mean that every tax, title deed fee or transaction cost associated with selling property in Turkey disappears after five years.
For example, title deed transfer procedures and their associated costs are separate from the question of whether the seller's profit is taxable as a capital gain.
For more information about the transfer process, see our guide to title deed transfer in Turkey for foreign buyers.
Is the Price Written on the Title Deed Important?
Yes. The declared acquisition and disposal values form part of the documentary history of the transaction, but capital gains calculations should be based on the applicable tax rules and supporting records rather than an informal estimate of profit.
Foreign buyers should therefore keep their purchase documentation, payment records, title deed documents and evidence of relevant transaction costs.
For international transactions, the banking side of the property purchase can also be important. You can read our guide to paying for property in Turkey as a foreign buyer, including bank transfers and DAB.
What If You Regularly Buy and Sell Properties?
The five-year capital gains rule should not be interpreted as a general tax exemption for professional or repeated property trading.
If property transactions are carried out with continuity and within a commercial organisation, the resulting income may be treated as commercial income rather than an individual capital gain.
This distinction is important for investors who regularly buy, renovate and resell apartments or who conduct multiple property transactions as an organised activity.
In such cases, the tax treatment can be fundamentally different from the sale of a privately owned property.
Should You Wait Until 5 Years Have Passed Before Selling?
The tax position is one factor to consider, but it should not be the only reason for deciding when to sell a property.
The owner should compare the potential tax consequence of an earlier sale with current market value, exchange rates, investment objectives, rental income, opportunity cost and the expected future value of the property.
A property owner who receives a strong offer before five years have passed may still find it financially sensible to sell after calculating the actual tax liability.
Conversely, an owner who is only a short period away from completing the five-year holding period may want to understand the tax difference before fixing the transfer date.
Why Is This Important When Buying Property in Turkey?
Capital gains tax is often considered only when an owner decides to sell. In practice, the future exit strategy should also be considered when purchasing.
A foreign buyer should retain clear records of:
- the acquisition date;
- the purchase price;
- title deed documentation;
- bank payment records;
- seller or buyer-paid taxes and fees;
- documented costs relevant to the acquisition or disposal; and
- delivery documentation where possession occurred before title registration.
These records can become important several years later when determining whether a sale falls within the five-year period and, if so, calculating the potential taxable gain.
If you are currently comparing property for sale in Alanya or planning to buy an apartment in Alanya, tax planning should therefore be considered as part of the wider investment decision rather than only at the moment of resale.
Frequently Asked Questions
Do I pay capital gains tax if I sell property in Turkey after 5 years?
For an individual selling a property acquired for consideration and held outside a business, the gain is generally outside the scope of capital gains taxation once the applicable five-year holding period has passed.
Do I automatically pay tax if I sell before 5 years?
No. A sale within five years can bring the gain within the capital gains rules, but the actual taxable amount must still be calculated. The acquisition cost, applicable indexation, eligible expenses and taxes, and the annual exemption can affect the result.
How much is the capital gains exemption in Turkey in 2026?
The capital gains exemption applicable to qualifying gains in 2026 is TRY 150,000.
How is the five-year period calculated?
The five-year holding period is calculated according to calendar days from the relevant acquisition date. It is not enough simply to compare the year of purchase with the year of sale.
What is normally considered the acquisition date?
The title deed registration date is generally used. In certain documented cases where the property was physically delivered and used before registration, an earlier actual-use date may be relevant.
Does kat mülkiyeti start a new five-year period?
A later conversion from kat irtifakı to kat mülkiyeti does not automatically restart the five-year period. The earlier kat irtifakı registration date may remain the relevant acquisition date.
Is inherited property subject to the five-year capital gains rule?
Property acquired without consideration, including inheritance, is treated differently. Gains from the disposal of such property are generally outside the capital gains regime discussed in this guide.
Does the rule apply to foreigners?
Foreign property owners should also consider Turkey's capital gains rules when selling property in Turkey. Nationality alone does not create a separate five-year holding rule.
Is the tax based simply on sale price minus purchase price?
No. The calculation can include indexation of the acquisition cost, eligible seller-paid expenses, taxes and fees, and the applicable annual exemption before the taxable gain is determined.
Is selling after five years completely tax-free?
Not in every sense. The five-year rule concerns capital gains taxation of the profit. Other costs and taxes connected with the property transfer can still apply.
Final Thoughts
The five-year rule is one of the most important tax considerations when selling privately owned property in Turkey.
The key distinction is simple: a sale within five years may create a taxable capital gain, while a sale after the five-year holding period is generally outside the scope of this capital gains rule.
However, sellers should not calculate their tax simply by subtracting the original purchase price from the selling price. The acquisition date, Yİ-ÜFE indexation, documented expenses, taxes and fees, the annual exemption and the nature of the transaction can all affect the final result.
For foreign owners and investors in Turkey real estate, keeping accurate documentation from the day of purchase can make the eventual resale process considerably easier.
Last updated: September 2026. This article provides general information and should not be treated as individual tax advice. Tax treatment can depend on the circumstances of the owner and transaction.
Share this post: